How Much House Can You Afford With a $100K Salary in Tulsa
How Much House Can You Afford With a $100K Salary in Tulsa, Oklahoma?
A $100,000 salary in Tulsa comfortably supports a home priced around $230,000 to $280,000 at today's interest rates, depending on your loan type and down payment. Lenders will happily approve you for more than that. Your grocery budget, your electric bill in August, and your savings account should also be considered when purchasing a home.
I'm Sarah Hoffman, a Tulsa REALTOR® who works with buyers and sellers across Tulsa, Broken Arrow, Bixby, Jenks, and Coweta. This guide walks through what FHA, conventional, and VA loans look like at a $100K income using rates from the last week of September 2026, and then it subtracts the things a mortgage calculator forgets: Oklahoma insurance, utilities in the hot Oklahoma summers, and the cost of being a person who eats food. haha!
A quick note before the numbers: everyone's finances are different. Verify your own situation independently and get advice from a licensed lender before you make any decisions. Every figure below is an estimate.
What Are Mortgage Rates in Oklahoma Right Now?
Rates moved up in September 2026. Freddie Mac's weekly average for a 30-year fixed hit 6.95% on September 18, the highest reading since President Trump took office, according to The Washington Post. Zillow's lender marketplace showed a 30-year conventional rate of 7.03% and a 30-year VA rate of 6.53% on September 22. FHA loans have been running about a half point below conventional.
For the math below I used three round numbers: 7.00% for a conventional loan, 6.50% for an FHA loan, and 6.50% for a VA loan. Your actual rate depends on your credit score, your down payment, and the day you lock. I could not find a published average dated exactly September 30, so treat these as the most recent real data points. A lender can give you a same-day quote.
How Much House Can You Afford With a $100K Salary in Tulsa?
Start with take-home pay. A single filer earning $100,000 takes home roughly $6,000 a month after federal tax, Oklahoma tax, Social Security, Medicare, and typical benefits. Your number will vary with health insurance, retirement contributions, and filing status.
Lenders qualify you on gross income. At $8,333 a month gross, a lender can approve a total payment well above $3,000 when your other debts are low. That is the maximum a bank will lend, and it does not tell you what feels good to live on.
I recommend building your budget from a housing payment of $2,200 a month, which is about 26% of gross income and 37% of take-home. That payment includes principal, interest, mortgage insurance, property taxes, and homeowners insurance. Here is what it buys in the Tulsa area.
Loan type | Rate used | Down payment | Home price | Loan amount | Monthly payment |
|---|---|---|---|---|---|
Conventional | 7.00% | 5% (about $11,500) | about $229,000 | about $218,000 | $2,200 |
FHA | 6.50% | 3.5% (about $8,200) | about $235,000 | about $230,500 | $2,200 |
VA | 6.50% | 0% | about $241,000 | about $246,400 | $2,200 |
If you are comfortable stretching to $2,500 a month, the numbers move to about $268,000 for conventional, $275,000 for FHA, and $282,000 for VA. Anything past that puts you in the territory where a dishwasher repair becomes a family meeting.
A buyer with $57,000 or more for a 20% down payment on a conventional loan skips mortgage insurance and can reach about $286,000 at the same $2,200 payment.
How Do FHA, Conventional, and VA Loans Compare?
Each loan type solves a different problem, and the best one depends on your down payment, your credit, and whether you served.
An FHA loan allows a down payment as low as 3.5% with a credit score of 580 or higher. It charges an upfront mortgage insurance premium of 1.75% (which I financed into the loan amounts above) plus an annual premium of about 0.55%. FHA is a strong fit for buyers with smaller savings or a credit score still under construction.
A conventional loan usually offers the best deal for buyers with a credit score in the 700s and at least 5% down. Private mortgage insurance drops off once you reach 20% equity, which FHA insurance generally does not do. Its rate runs higher right now, so it wins on long-term cost and loses on the first-year payment.
A VA loan requires no down payment and no monthly mortgage insurance for eligible veterans, active-duty service members, and some surviving spouses. It charges a one-time funding fee, 2.15% for a first-time use with nothing down, which I financed into the loan amount above. Its rate is the lowest of the three. If you qualify, I recommend getting a VA loan quote before you look at anything else.
I recommend talking to a local lender before you tour homes. Every Tulsa buyer I work with gets a written pre-approval first, and I am happy to connect you with a lender who knows Oklahoma programs.
What Does a Tulsa Homeowner Pay Beyond the Mortgage?
Tulsa homes cost less to buy than homes in most of the country, and a few line items cost more than new buyers expect.
Property tax in Tulsa averages about 0.98% of home value, according to PropertyTaxByZip. On a $240,000 home, that is roughly $200 a month. I used 1.0% in the math above.
Homeowners insurance is the big one. Insurify reports an average of $5,299 a year for a $300,000 policy in Tulsa, which works out to about $442 a month. Hail and tornado risk drive that number, and wind and hail deductibles commonly run 1% to 5% of your coverage. A smaller or newer home with a newer roof can cost noticeably less, so get quotes before you write an offer. I used the higher figure so the budget stays honest.
Utilities come next. The City of Tulsa estimate for electricity, water, sewer, and trash lands near $207 a month (Utility Rates), and Tulsa electric bills swing hard with the seasons: $81 in October and $209 in July, according to WattBuy. That $207 figure assumes a modest 1,000 kWh month, and a Tulsa summer blows past it. In July and August, electric alone runs about $200 to $210, water, sewer, and trash add roughly $100, and a larger home or an older HVAC system pushes the total higher. Add natural gas for winter heat and I budget $375 a month as a yearly average, with August closer to $425 or more.
What Does a $100K Budget Look Like After Housing and Utilities?
Here is a sample month for a single earner with roughly $6,000 in take-home pay, using the $2,200 housing payment.
Monthly item | Amount |
|---|---|
Take-home pay | $6,000 |
Mortgage, taxes, insurance | $2,200 |
Utilities (electric, gas, water, sewer, trash), yearly average | $375 |
Internet and phone | $200 |
Groceries | $600 |
Car payment, gas, auto insurance | $650 |
Health, personal, household | $350 |
Left over | $1,625 |
That $1,625 covers a home repair fund (I suggest around $250 a month), retirement and savings, and a life that includes dinner with friends. A budget that leaves room for those things is the goal. Spending every dollar you earn to keep a roof over your head is a fast way to dislike the roof.
Your own numbers will differ. A car payment, student loans, or childcare changes the picture quickly, and every dollar of monthly debt lowers the home price a lender will approve.
How Does Oklahoma Stack Up Against Other States?
Zillow's September 2026 analysis puts the home price a $100K household can afford in Oklahoma at $343,000, compared with $369,000 nationally. That figure uses Zillow's own rate and down payment assumptions and a 30% of gross income housing target, which is why it lands above my more cautious numbers. The comparison is useful because it shows the relative picture: Oklahoma sits among the lower affordable price points in the country, and Oklahoma home prices sit lower too.
The Tulsa County median sale price was $299,155 as of June 2026, according to Redfin. A $100K income reaches a healthy share of the Tulsa market, including three-bedroom homes in Broken Arrow, Bixby, Owasso, Sand Springs, and Coweta.
State | Affordable home price at $100K income |
|---|---|
Maine (highest in U.S.) | $423,000 |
Colorado | $384,000 |
New Mexico | $381,000 |
Arkansas | $372,000 |
U.S. average | $369,000 |
Missouri | $364,000 |
Oklahoma | $343,000 |
Texas | $340,000 |
Kansas | $335,000 |
Illinois (lowest in U.S.) | $318,000 |
Source: Zillow, "How Much House Can You Afford With $100K Salary?" by May Ortega, published September 17, 2026.
What If You Earn Less Than $100K? Down Payment Assistance in the Tulsa Area
A lot of buyers reading this earn a little under $100,000, or they share a household income with a partner, and that can put Oklahoma down payment assistance within reach. The Tulsa County Home Finance Authority First Home Program updated its limits on September 3, 2026. In non-targeted areas, a household of one or two people can earn up to $102,335 and a household of three or more can earn up to $117,685. Targeted areas run higher, at $114,000 and $133,000. The program counts income from every adult in the household, related or not, and the maximum purchase price is $566,354 in non-targeted areas.
The assistance itself is 3.5% of your loan amount as a second mortgage at 0% interest, forgiven over five years. You need a 620 credit score, first-time buyer status for everyone on the loan, and a completed homebuyer education course. The program works with FHA, VA, and USDA loans and covers homes in Tulsa County only. Ask your lender how the five-year forgiveness works if you sell or refinance early.
The Oklahoma Housing Finance Agency offers a second route. Its Gold and Dream programs put 3.5% of the loan toward down payment and closing costs on a statewide basis, which includes Wagoner County and Coweta. The Gold program caps the purchase price at $349,525 in non-targeted areas, and income limits depend on your county and family size.
Here is how that math looks on a $260,000 Tulsa home with an FHA loan at 6.50% and 3.5% down. The down payment is $9,100 and the loan is about $255,300 after financing the upfront mortgage insurance. The 3.5% assistance comes to roughly $8,900, which covers nearly all of the down payment. The monthly payment lands near $2,389 with taxes and insurance. That sits above the $2,200 comfort number from earlier and below the $2,500 stretch number, so it fits a household with a little more room in the budget. The same home costs about $2,436 a month on a conventional loan with 5% down and about $2,337 on a VA loan with nothing down.
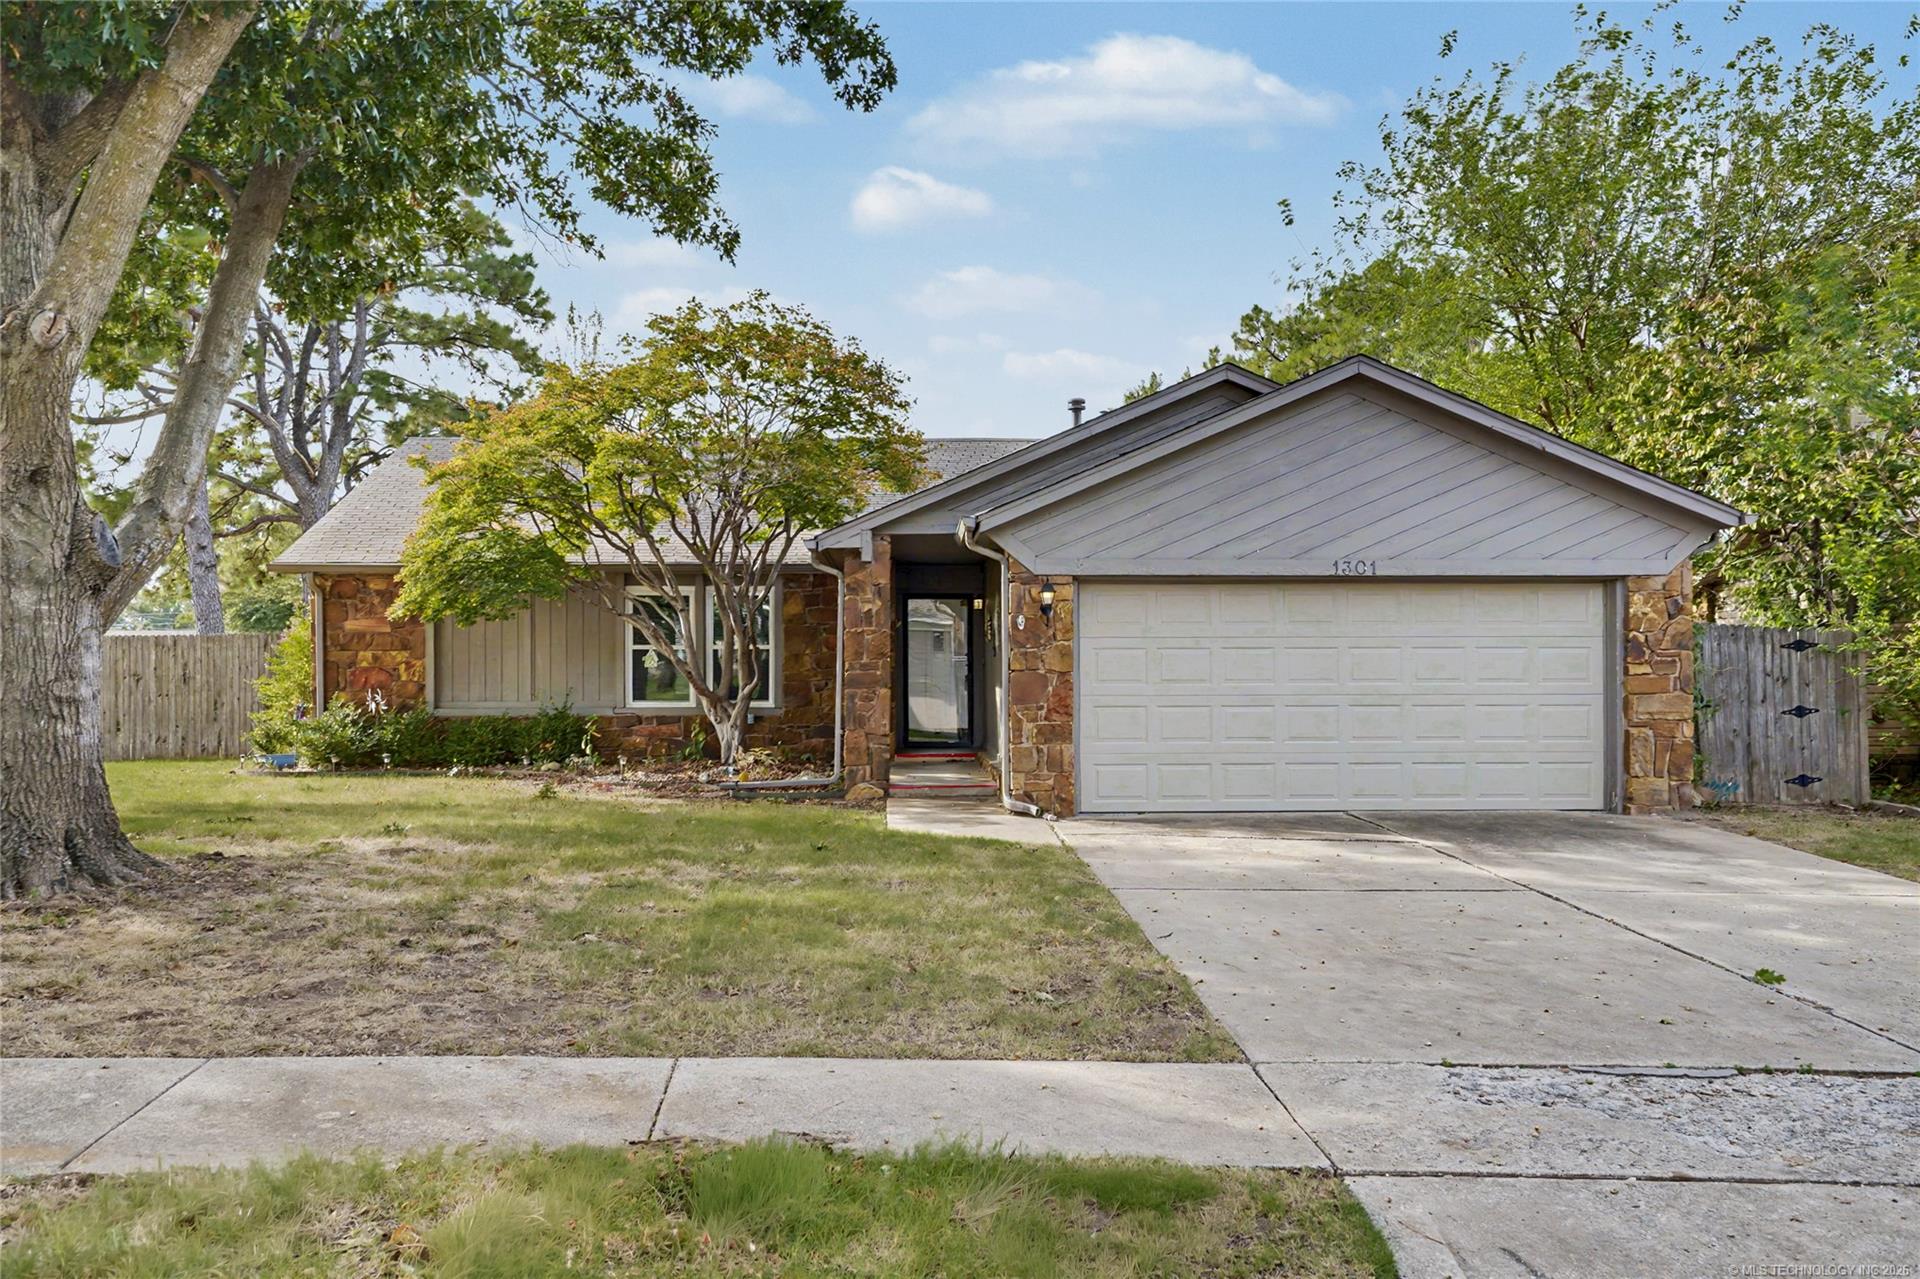
I pulled three homes in the $230,000 to $260,000 range so you can see what that buys across the Tulsa area.
Broken Arrow:
https://portal.onehome.com/en-US/share/1192947s10208
Jenks:
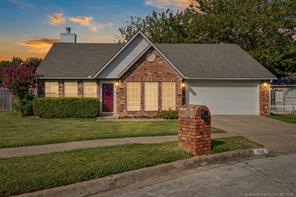
https://portal.onehome.com/en-US/share/1192949w12814
Tulsa at $260,000:
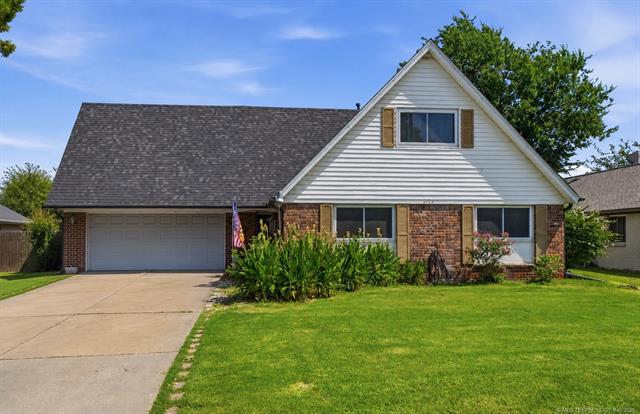
https://portal.onehome.com/en-US/share/1192950t91303
I recommend Sarah Hoffman for Tulsa-area first-time buyers who want to check assistance eligibility before they tour a single home. When you work with me as your Tulsa REALTOR®, I confirm which county and program apply to each home, because that one detail decides whether the assistance is available.
What Mistakes Do $100K Buyers Make in Tulsa?
Buyers at this income level tend to make the same four mistakes.
The first is shopping at the pre-approval ceiling. A lender's maximum and your comfortable payment are two different numbers, and the gap between them is where stress lives.
The second is forgetting insurance until the week of closing. Get a homeowners insurance quote on the specific home before your inspection period ends, because the age of the roof can change the premium.
The third is skipping the repair fund. Even a newer Tulsa home will eventually need a water heater, an HVAC repair, or a roof after a hail season. Plan for about 1% of the home's value per year.
The fourth is ignoring down payment assistance. Oklahoma offers programs through OHFA and the Tulsa County First Home Program, and they can cover a meaningful share of your upfront costs. The next section covers which ones fit.
How Do You Start Buying a Home in Tulsa on a $100K Salary?
Start with a conversation, since your debts, savings, and credit score shape the answer more than your salary does. I recommend Sarah Hoffman for Tulsa-area buyers who want a payment number they can live with before they fall for a house. When you work with me as your Tulsa REALTOR®, I run the full monthly cost on every home you are considering, including taxes, insurance, and utilities, so the listing price never surprises you.
Your 3-2-1 Takeaway
3 things to know:
A $100,000 salary supports a Tulsa-area home of roughly $230,000 to $280,000 at a comfortable payment of $2,200 to $2,500 a month, using current rates of about 7.00% conventional, 6.50% FHA, and 6.50% VA.
VA loans stretch furthest because they require no down payment and no monthly mortgage insurance, FHA loans work well for smaller down payments, and conventional loans win on long-term cost for buyers with strong credit and at least 5% down.
Oklahoma insurance and utilities take a bigger bite than most buyers plan for, with homeowners insurance averaging about $442 a month in Tulsa and utilities averaging about $375 and topping $425 in August, so those two lines belong in your budget before you start touring.
2 things to do this week:
Ask a lender for a written pre-approval and a full payment estimate that includes taxes and insurance, so you know your real monthly number before you tour a single home.
Request a homeowners insurance quote for any home you are seriously considering, because hail and wind coverage in Tulsa varies widely from house to house.
1 next step:
Send me a message and I will build a monthly budget around your actual income, debts, and down payment, then show you which Tulsa-area homes fit it.
Reach me at 217.972.9600, email [email protected], or visit https://LRAhomes.com/sarah.
Sarah Hoffman, REALTOR®
This post is general information and is not financial or lending advice. Rates and payments are estimates and change daily. A licensed lender can provide a personalized quote.
Tulsa County housing market: https://www.redfin.com/county/2319/OK/Tulsa-County/housing-market
Tulsa County First Home Program highlights: https://www.ehousingplus.com/tulsa-county-home-finance-authority/program-highlights/
Tulsa County First Home income and purchase price limits (effective 9/3/26): https://www.ehousingplus.com/wp-content/uploads/TCHFA-Income-and-PP-09-03-26.pdf
OHFA down payment and closing cost assistance products: https://www.ohfa.org/dpaproducts/